In which areas does management accounting need to be reimagined?
The role of controlling remains central to corporate management. However, the operating environment is changing: digitalization, AI, and new demands for collaboration and speed are also posing challenges for controlling.
As part of our series “5 Theses on Controlling in Discourse,” ICV Board Member Pia Burkarth focuses on the further development of tools, working methods, and processes in controlling.
🔈 THESIS 4
: “The core functions of management accounting remain the same, but they require realigned tools as well as adapted work methods and processes.”
💬 We’d love to hear your thoughts:
In your opinion, which tools and methods in controlling need to change the most?
Where do you see the greatest need for adaptation in practice?
What is your opinion on this, what are your experiences? We look forward to discussing this with you!
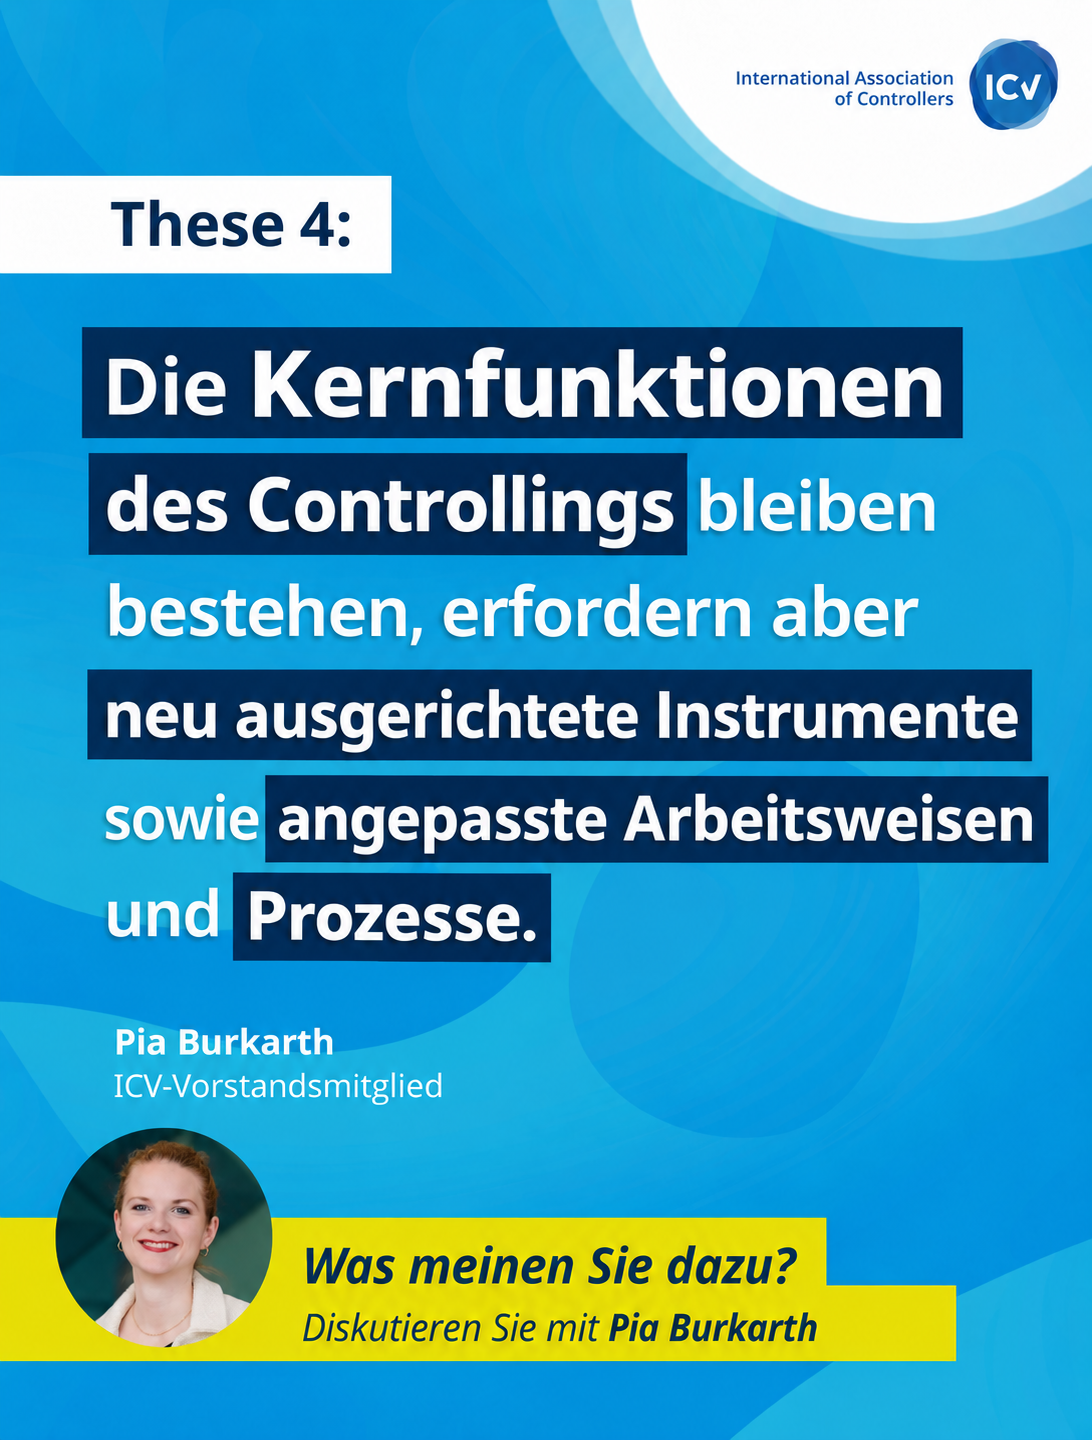
Pia Burkarth is a member of the ICV Board of Directors and, as Finance Director of Veridos Mexico S.A. de C.V., is responsible for accounting, controlling, procurement, human resources, and legal and compliance. As an author, speaker, and lecturer, she contributes her expertise in controlling and financial management to professional discourse and education. She holds a master’s degree in accounting, finance, and controlling and is a certified agile organizational developer and agile coach.